

The World That Was
| $ ‘000 |
2013 |
2014 |
2015 |
2016 |
2017 |
|---|---|---|---|---|---|
| Revenue |
1,000 |
1,200 |
1,440 |
1,728 |
2,074 |
|
Growth |
20% |
20% |
20% |
20% |
|
| EBITDA |
400 |
480 |
576 |
691 |
829 |
|
Margin |
40% |
40% |
40% |
40% |
40% |
| PAT |
200 |
240 |
288 |
346 |
415 |
|
Margin |
20% |
20% |
20% |
20% |
20% |
 So when you find a 20/20, the valuation is also pretty straight forward. You are going to paying somewhere in the region of 4x EBITDA. EBITDA is very bad short hand for the amount of cash that a business generates in a year. So when you say that you are paying 4x EBITDA you are effectively paying for 4 years of the business cash flow. 4x EBITDA is typical for a 20/20 business and the valuation table below shows why:
2013 Valuation |
|
| EBITDA Multiple | 4x |
| Company Value ($ ‘000) | 4,000 |
2017 Valuation |
|
| EBITDA Multiple | 6x |
| Company Value ($ ‘000) | 12,442 |
| TMB | 3.11 x |
The World That Is
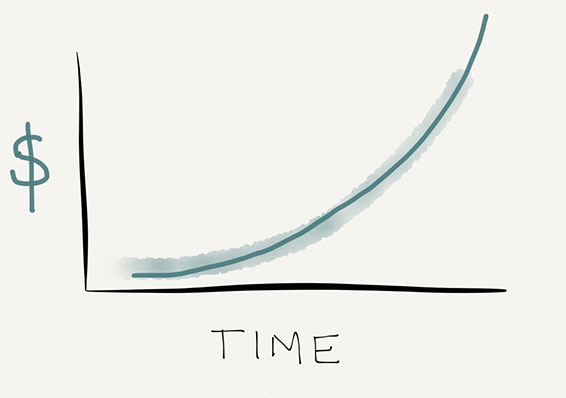 Times are changing. The staid 20/20’s have been replaced by the sexy hockey sticks. A hockey stick is a company whose growth trajectory looks like this:
| $ ‘000 |
2013 |
2014 |
2015 |
2016 |
2017 |
|---|---|---|---|---|---|
| Revenue |
1,000 |
1,750 |
3,063 |
5,359 |
9,379 |
|
Growth |
75% |
75% |
75% |
75% |
|
| EBITDA |
200 |
350 |
613 |
1,072 |
1,876 |
|
Margin |
20% |
20% |
20% |
20% |
20% |
| PAT |
100 |
175 |
306 |
536 |
938 |
|
Margin |
10% |
10% |
10% |
10% |
10% |
2013 Valuation |
|
| EBITDA Multiple | 4x |
| Company Value ($ ‘000) | 800 |
2017 Valuation |
|
| EBITDA Multiple | 10x |
| Company Value ($ ‘000) | 18,758 |
| TMB | 23.45 x |
NO DEAL!
After the hockey stick entrepreneur has stormed of private equity gal’s office, the adviser remembers that he has a friend from business school who is living the dream as a late stage VC. The Adviser shoots his fried a teaser about hockey stick. The friend goes all googley-eyed when he sees the early stage of a billion dollar business in a country with a large consumer market. Venture capital investor shoots off a term sheet to hockey stick entrepreneur. The Adviser reviews the term sheet and shows the hockey stick entrepreneur the type of return this deal implies:
2013 Valuation |
|
| EBITDA Multiple | 20x |
| Company Value ($ ‘000) | 4,000 |
2017 Valuation |
|
| EBITDA Multiple | 10x |
| Company Value ($ ‘000) | 18,758 |
| TMB | 4.69 x |
DEAL!
The World That Will Be
 This state of affairs is not going to change for the foreseeable future. The private equity girl will not be able to do tech deals because the valuations are completely outside her understanding. She knows too much about Nigeria to accept the risk implied in these valuations.
Some of these deals will make mega money – there should be a few $500 million – $1 billion companies made off the back of the various raises being done in the market right now.
As a result Private Equity Girl will no longer be the only local investor in town. Springing fully formed like Athena from the head of Zeus, Nigerian Venture Capital Girl will arise. Unlike Private Equity Girl, she will be tasked specifically to invest in these hockey stick opportunities. Her Chi will be strong and she will do many deals in the market.
Until then tech folk, be nice to your foreign investors, they are likely to be the only ones you’ll get for a while.