

Kenswitch, Kenya’s largest independent payments switch, has launched a domestic card scheme that will let banks and other financial institutions issue physical and virtual cards on its network, putting a new player into the country’s mobile money-dominated market.
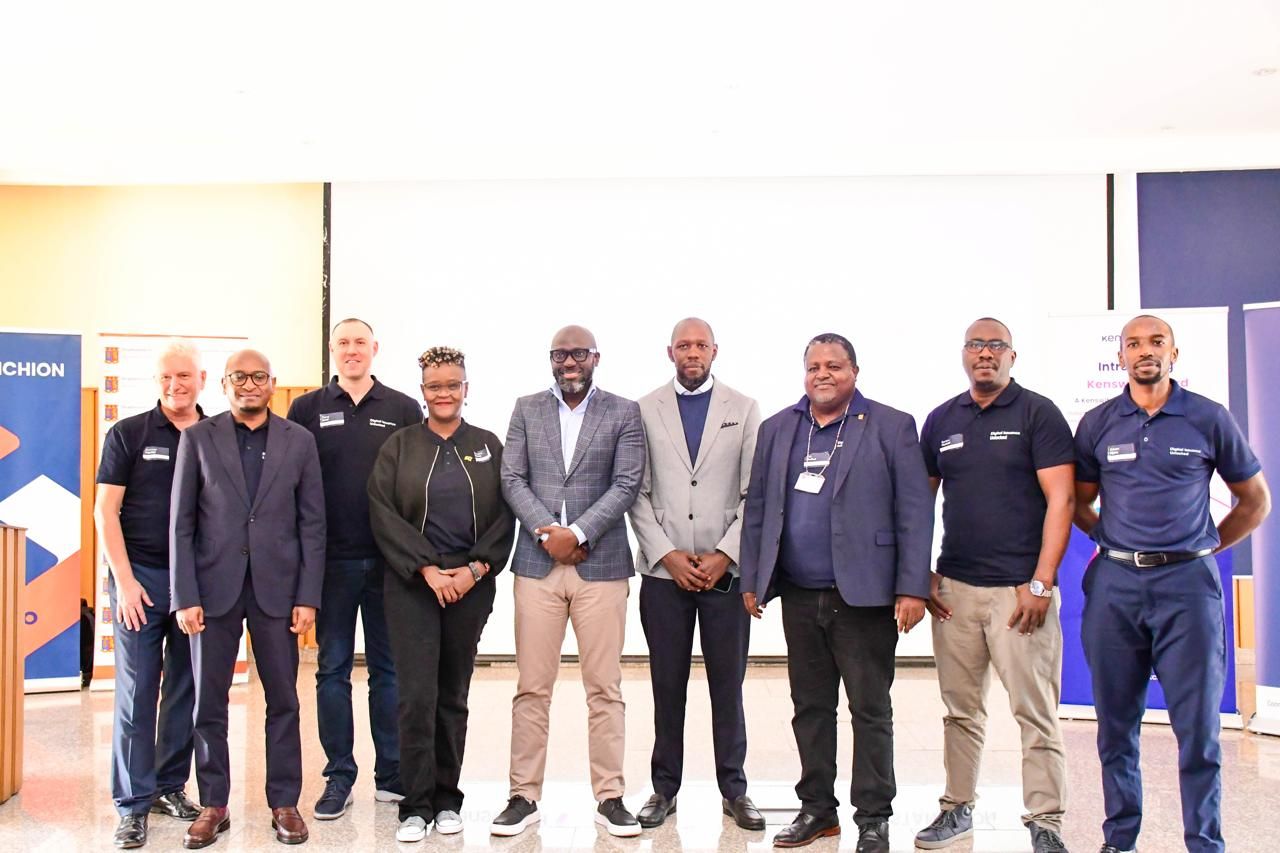
The company unveiled the Kenswitch Card on Tuesday at Strathmore University, where it demonstrated a digital card issuance system built with TAI FINTECH, a fintech innovation venture affiliated with the university, and Stanchion Payments, a global payments technology company, it said in a statement.
The launch expands Kenswitch’s role beyond switching, connecting banks and other financial institutions to route payments. With its own card scheme, the company can now support card issuance and acceptance, giving financial institutions another option for domestic card payments.
Kenswitch is entering a card issuance market where global payment giants Visa and Mastercard are already deeply embedded in Kenya’s banking system. Banks, including KCB and I&M Bank, continue to launch new Mastercard products, while Kenyan banks also issue Visa cards to their customers, especially credit cards. In July 2026, Kenya held 11.16 million debit cards, 2.26 million prepaid cards, and 340,852 credit cards, according to the Central Bank of Kenya (CBK).
“Through partnerships such as this, Kenswitch is positioning the local payments ecosystem to participate in the future of tokenised and digital payments while continuing to develop solutions that are relevant to Kenyan financial institutions and consumers,” Kenswitch’s chief executive officer John Mukono said in a statement.
Kenswitch’s proposition is to give banks more of the card infrastructure locally. The company said its scheme will run across its network of more than 2,200 automated teller machines (ATMs), 50,000 point-of-sale (PoS) terminals, and 80,000 agent outlets. It did not disclose which financial institutions will issue the cards, when consumers will receive them, or how the scheme’s pricing will compare with existing card networks.
During the launch, Kenswitch and its partners demonstrated a customer opening an account digitally and receiving a virtual card almost immediately. The card could be frozen and unfrozen, generate dynamic security codes, and authenticate online purchases through app notifications or email.
Locally-issued cards are not unique to Kenya. In 2023, Nigeria launched AfriGo, its national domestic card scheme built by the Central Bank of Nigeria (CBN) in partnership with the Nigeria Inter-Bank Settlement System (NIBSS), the country’s payment switch. In September, NIBSS managing director and CEO Premier Oiwoh said AfriGo has issued over 1 million cards in Nigeria, processing about ₦70 billion ($52.8 million) in transactions.
Domestic card schemes keep more of the infrastructure and economics of local card payments within the country, giving banks a local rail for domestic transactions and reducing reliance on foreign networks.
Kenswitch is also looking beyond the physical card. The country is exploring partnerships with technology companies and mobile device manufacturers that could allow virtual Kenswitch cards to be added directly to supported smartphones for contactless Tap to Pay transactions.
“We are looking beyond the card itself to how consumers will use payment credentials in the future,” Mukono said.
With rising smartphone adoption in Kenya, Kenswitch is also looking beyond the physical card. Smartphones made up 63.7% of the 78.7 million mobile phones connected to Kenyan networks as of March 2026, according to the Communications Authority of Kenya (CAK), giving the company a growing base of devices where virtual cards and Tap to Pay could live. In December 2025, the regulator said Kenya’s smartphone penetration reached 92.9%.
Though smartphone penetration and card use in Kenya are growing, the country’s payments ecosystem is still dominated by mobile money. Kenya had 94.4 million registered mobile money accounts and 575,400 active agents in July, with agents handling KES 728.7 billion ($5.6 billion) in cash-in and cash-out transactions, according to the CBK. This was far more than the KES 38.04 billion ($293.6 million) Kenyans spent using prepaid, credit, and debit cards—including card payments processed at PoS terminals—in the same month.
Despite card payments trailing mobile money in Kenya, card use is still growing. Since January, debit cards have increased 4.2% from 10.7 million, while prepaid cards have grown nearly 20%.
Safaricom’s M-PESA, the mobile money arm of Kenya’s largest telco, is already bringing cards into that mobile-first market. Its M-PESA GlobalPay virtual Visa card had 316,500 active users as of March 2026 and processed 8.5 million transactions worth about KES12 billion ($92.7 million) during the financial year, a 38% increase from the previous year. In August, Safaricom added its Fuliza overdraft facility to GlobalPay, allowing customers to fund online purchases through the credit service.
Kenswitch is targeting a different part of this market: the financial institutions that want to issue cards and process domestic transactions without relying entirely on an international network.
The launch follows Kenswitch’s April partnership with Visa to explore new payment solutions, merchant acceptance, payment processing, and settlement in Kenya. Both companies also plan to explore emerging payment technologies, giving Kenswitch access to Visa’s global payments expertise as it builds out its own domestic card infrastructure.
True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.